

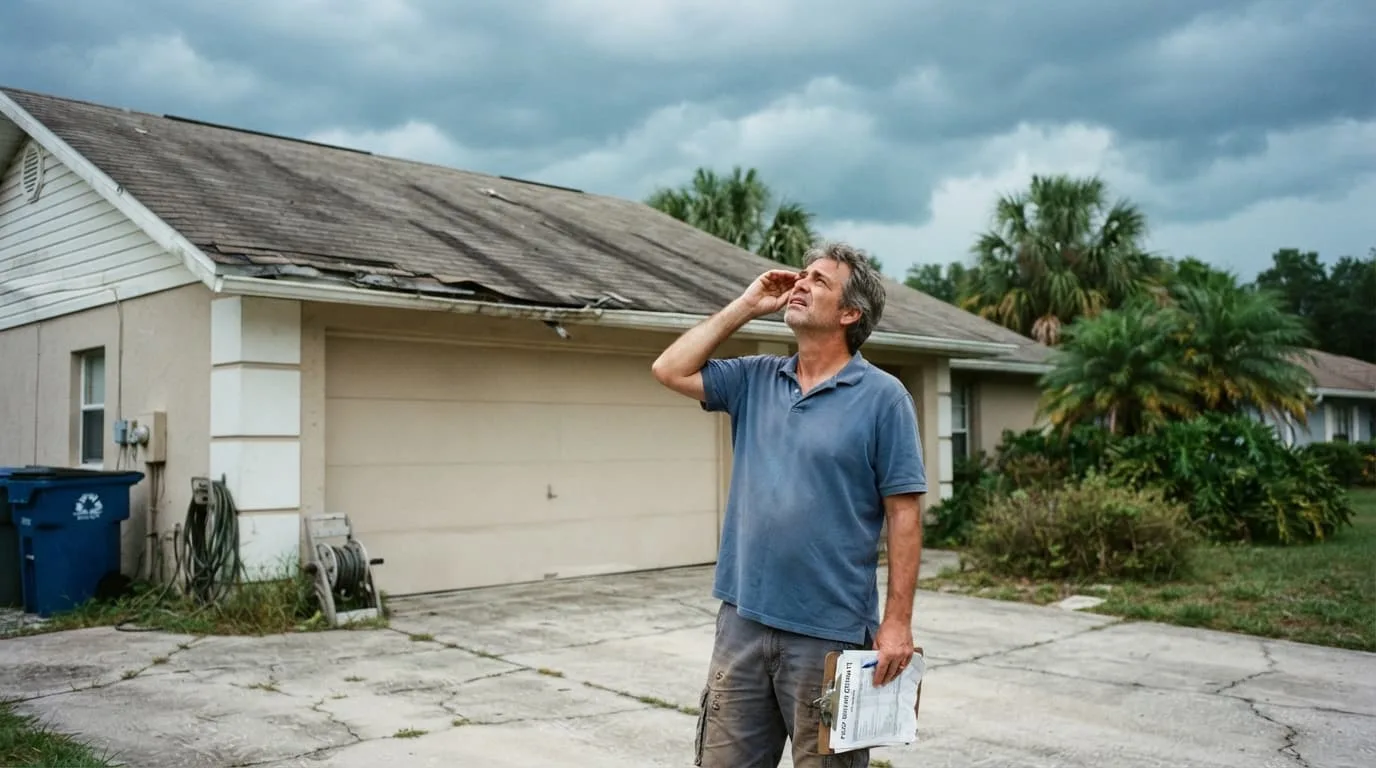
We dug into the latest Florida Office of Insurance Regulation data, and the numbers tell a story that every Lakeland homeowner with storm damage needs to hear. Hurricane Isaias generated roughly 55,000 claims across Florida, but nearly a quarter of the early closures came back with no payment, and the most common reason wasn’t what you’d expect. With Florida’s one-year claim deadline now ticking, the window to get roof repair Lakeland homeowners need is closing faster than most people realize.
Three Surprising Findings
The top reason claims closed without payment wasn’t a denial.
Florida OIR introduced a new reporting category this year called “administrative reasons”, claims withdrawn by the insured, duplicate filings, or cases where the insurer could not reach the policyholder. That category was the most-cited explanation for no-payment closures in early Isaias reporting. Many homeowners filed before they understood their deductible or whether they had covered damage.
Florida’s re-roof permit share has collapsed to pre-Irma lows.
Re-roofing accounted for just 7.6% of all Florida permits in Q3 2026, the lowest since 2017, according to Carbon Arc’s analysis. Meanwhile, carriers are reporting tens of thousands of new storm claims. Homeowners are sitting on damage without repairing it, and that backlog doesn’t disappear. It compounds.
Filing a claim correlates with much higher premiums, even legitimate ones.
The University of North Florida surveyed 1,511 Florida homeowners and found that 53% of those who pursued at least one claim reported premiums rising 50% or more over five years, compared to 47% overall. The quality of the claim matters. A well-documented, properly scoped filing is less likely to trigger downstream underwriting pain than a withdrawn or sloppy one.
Key Findings
- Approximately 55,000 residential property claims were filed in Florida within two weeks of Isaias, with estimated insured losses at $651 million (Florida OIR, via Insurance Journal, Nov. 9, 2026).
- 22% of residential claims had been closed by Oct. 20, many without payment; “administrative reasons” was the most frequently cited no-payment category (Florida OIR, via Insurance Journal).
- Florida law gives homeowners 1 year from the date of loss to file a new or reopened property insurance claim, and 18 months for supplemental claims (Florida Statutes §627.70132).
- Karen Clark & Company estimated ~$3 billion in total insured losses across the Southeastern U.S. from Isaias (Carrier Management, Oct. 15, 2026).
- Re-roof permits were just 7.6% of all Florida permits in Q3 2026, the lowest since before Hurricane Irma in 2017 (Carbon Arc, Oct. 21, 2026).
- 47% of surveyed Florida homeowners reported premium increases of 50%+ over five years; among those who filed claims, that figure rose to 53% (University of North Florida poll, via Sun Sentinel, Sept. 24, 2026).
What This Means for Lakeland Homeowners
The Isaias data reveals a pattern that should concern anyone with a roof in Central Florida: claims are being filed, but a significant share are closing without payment, often for reasons that professional documentation and pre-filing inspection could have prevented. The one-year deadline under Florida law isn’t a suggestion. For Isaias, which made landfall Oct. 9, 2026, that points to October 9, 2027. Homeowners who wait until the final weeks lose leverage, evidence quality, and options.
The permit data adds another layer. With re-roofing activity at a nine-year low despite active storm seasons, there’s a growing backlog of deferred roof work across the state. In Lakeland and Polk County, where afternoon storms are routine and hurricane exposure is real, that backlog creates risk: small issues become water intrusion, and water intrusion becomes structural damage.
Expert Quote
“The OIR’s administrative reasons category is the tell. It means thousands of homeowners filed claims before they had a clear picture of what was damaged, what their deductible would absorb, and what documentation their insurer would need. That is a preparation problem. We inspect the roof and write down what we find. The homeowner sends that file to the carrier. We do not file the claim and we do not adjust it. With the one-year deadline now running, Lakeland homeowners cannot afford to learn this lesson the hard way.” - Issac Turpin, CEO of True Corp and founder of True Roofers
Methodology
This analysis draws on Hurricane Isaias claims data reported by Florida carriers to the Florida Office of Insurance Regulation and published by Insurance Journal (Nov. 9, 2026), Florida Statutes §627.70132, Karen Clark & Company’s insured loss estimate (Oct. 15, 2026), Carbon Arc’s Q3 2026 Florida permit analysis (Oct. 21, 2026), and a University of North Florida Public Opinion Research Lab survey of 1,511 Florida homeowners conducted July 16 - 31, 2026 and reported by the Sun Sentinel.
The Clock Is Running
If your roof may have storm damage, don’t wait until the deadline is weeks away.
Read the complete analysis: Roof Repair Lakeland Deadline Looms as Florida’s 1-Year Claim Window Closes.
And if you’re in Lakeland or the surrounding areas and need a professional assessment, our roof repair team can inspect, document, and help you decide what comes next, before the window closes.
